EB-5 I-829 Process: From Conditional Green Card to Removal of Conditions


The EB-5 I-829 process is how investors apply to remove the conditions on their permanent resident status. The petition requires evidence of the qualifying investment and job creation.
Preparation should begin before the filing window opens, with the investor’s attorney and regional center coordinating the necessary records.
When to File: The EB-5 I-829 Process
Form I-829, Petition by Investor to Remove Conditions on Permanent Resident Status, must generally be filed during the 90-day period immediately before the second anniversary of obtaining conditional permanent residence.
As explained in the USCIS EB-5 process overview, conditional residence begins when USCIS approves adjustment of status or when the investor enters the United States with an immigrant visa. It does not begin with I-526E approval or delivery of the physical green card.
Confirm the filing window using the card’s “Resident Since” date and immigration records. Eligible spouses and children may be included in the petition; counsel should confirm the family’s filing arrangements, particularly when members obtained conditional residence on different dates.
What Evidence Does USCIS Review?
USCIS reviews whether the investor met the applicable investment, sustainment and job creation requirements. The job creation requirement generally calls for at least 10 qualifying full-time jobs per investor, created or expected to be created within a reasonable time under applicable rules.
For regional center projects, job creation may be established through permitted economic methodologies. The expenditures, revenues or other inputs used in the analysis need supporting records.
What USCIS reviews | Typical supporting evidence |
Qualifying investment | Transfer records, bank statements and investment documents. |
Investment sustainment | Records showing the investment was maintained for the applicable period. |
Job creation | An economic report and records supporting the job creation calculations. |
USCIS’s suggested order of I-829 documentation provides a starting point. The evidence package should reflect the project’s methodology and the investor’s circumstances.
Discuss ARCFE’s project monitoring and documentation approach with our team, and learn how these support your attorney’s I-829 preparation.
How the Investment Sustainment Rules Apply
The relevant framework depends on when the underlying EB-5 immigrant petition was filed.
For petitions filed before March 15, 2022, investors generally must sustain their investment throughout the two-year conditional residence period. For petitions filed on or after that date, USCIS guidance interprets the requirement as at least two years from when the full qualifying investment is contributed and placed at risk, including being made available to the job-creating entity as applicable.
For post-RIA investors, the investment period therefore does not necessarily match the conditional residence period. Completing the applicable sustainment period does not create a right to immediate repayment; the investment documents may provide for a longer term.
What Happens While I-829 Is Pending?
A properly filed I-829 extends conditional permanent resident status while USCIS reviews the petition.
Under current USCIS policy, the receipt notice and expired conditional green card together document a 48-month extension of the card’s validity, measured from its expiration date.
Keep both documents. Ordinary permanent resident travel requirements continue to apply. If the documented extension is nearing its end while the case remains pending, contact counsel and USCIS about updated evidence of status.
USCIS may request additional evidence or require an interview. The extension is not an adjudication deadline; check the USCIS processing times tool for current estimates.
I-829 Approval and Capital Repayment Are Separate Milestones
I-829 approval removes the conditions on permanent resident status and generally results in a 10-year green card.
Approval does not itself trigger capital repayment. Repayment depends on the offering documents, applicable investor conditions, available funds and project developments.
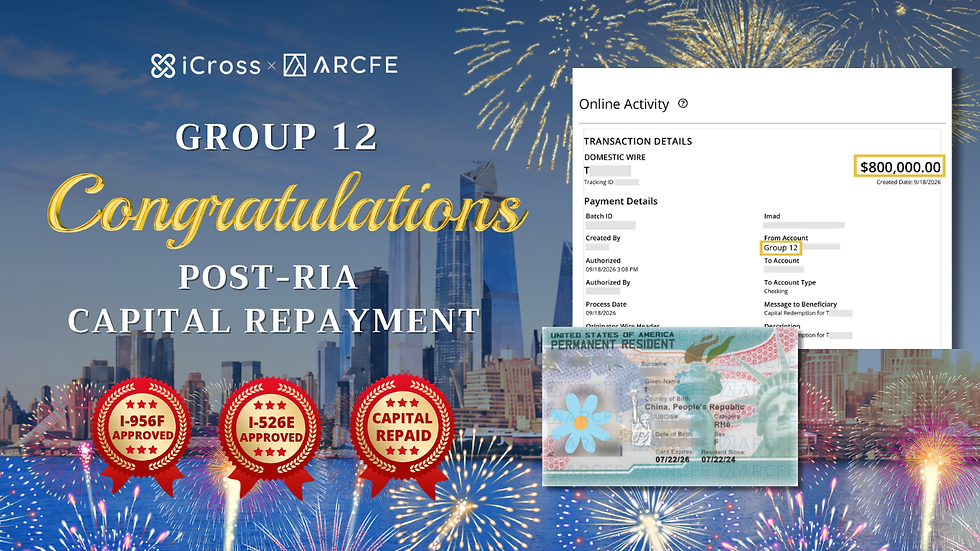
For example, a Group 4 investor’s I-829 was approved on July 1, 2026. The investor subsequently received principal after satisfying the relevant repayment conditions. This illustrates how the two milestones can occur at different times.
Our EB-5 capital repayment guide explains the distinction between project loan repayment and principal distributed to investors.
The ARCFE Perspective: Preparing Beyond the Initial Petition
ARCFE combines EB-5 project management with iCross Capital’s New York real estate credit experience. Our focus includes project progress, capital deployment and documentation supporting job creation.
When evaluating a regional center, ask how it maintains project records, communicates updates and coordinates with immigration counsel as I-829 approaches. These capabilities deserve attention alongside its initial approval history.
ARCFE supports the project side of the process. Your immigration attorney assesses your family’s eligibility and prepares the legal filing.
Speak with the ARCFE team about our project management approach and current New York EB-5 opportunities.
This article is for general information and does not constitute legal, tax or investment advice. Filing requirements depend on applicable law and individual circumstances. Past performance does not guarantee future results.
Recent ARCFE EB-5 Principal Repayment Highlights
Explore ARCFE’s latest EB-5 principal repayment milestones across pre-RIA and post-RIA projects. Click any image below to read the full project update.

Explore Current New York Real Estate-Backed EB-5 Opportunities


Considering EB-5 for Your Family?
Speak with an iCross × ARCFE EB-5 specialist to discuss your immigration goals, timeline, and available investment opportunities.
Related ARCFE Resources
Review important travel, residency, tax and immigration considerations after receiving a conditional green card.
Understand how senior debt, mezzanine financing and equity differ in repayment priority and risk exposure.