
How EB-5 Real Estate Loans Are Repaid: Sales, Refinancing, and Timing

Updated: 1 day ago
In a loan-based EB-5 real estate investment, the maturity date establishes when the project borrower is scheduled to repay the loan. The exit strategy explains how that repayment is expected to be funded.
For real estate developments, repayment typically depends on property sales, refinancing, or another planned transaction involving the completed asset.
Understanding these financing arrangements helps EB-5 investors evaluate a project's financial structure and the experience of the team managing it.

1. What Are the Main Repayment Sources for EB-5 Real Estate Loans?
In a typical loan-based regional center investment, EB-5 capital is pooled through a New Commercial Enterprise (NCE), which provides financing to the project's Job-Creating Entity (JCE).
The JCE's repayment strategy generally reflects the type of development and its underlying business plan.
Repayment Source | How It Works |
Property Sales | Proceeds from completed residential unit sales are used to repay project financing. |
Refinancing | A completed or stabilized property obtains new financing to repay the existing development loan. |
Asset Sale | Proceeds from selling the completed property provide funds to repay outstanding financing. |
Some developments may use a combination of these sources. A condominium project may generate repayment proceeds as units close, while an income-producing property may rely on refinancing after it reaches operating stability.
The key question is whether the proposed repayment source aligns with the property's business model, expected market demand and financing obligations.
The OCC's Commercial Real Estate Lending handbook provides a broader framework for prudent development lending and repayment analysis.
For a closer look at how financing is arranged at the project level, see ARCFE's guide to EB-5 Sources and Uses of Funds.
Explore the Financing Behind an EB-5 Project
Discuss project structure, repayment planning and current New York real estate-backed EB-5 opportunities with iCross × ARCFE.
2. How Do Loan Maturity and Extension Provisions Work?
An EB-5 project loan generally has a contractual maturity date, when the borrower is expected to repay the outstanding financing.
Depending on the loan agreement, financing may also include defined extension options. These provisions can accommodate the project's development and financing timeline when the contractual conditions are satisfied.
For example, a construction loan may be structured around the expected completion, sales or stabilization period of the property.
From a lending perspective, maturity and extension terms should be evaluated alongside the anticipated repayment source. The OCC's commercial lending underwriting guidance identifies repayment programs, maturities and financing terms as important parts of credit evaluation.
For EB-5 investors, the practical question is how the loan's contractual timeline fits the project's business plan.
3. Why Real Estate Market Fundamentals Matter to Repayment
A credible repayment strategy begins with an understanding of the local real estate market.
For projects relying on residential sales, relevant factors include neighborhood demand, comparable transactions, projected sales activity and the development's competitive position.
For properties expected to refinance, lenders may evaluate occupancy, operating income, valuation and financing available for stabilized assets.
In New York City, public resources such as the NYC Department of Finance's rolling property sales data and the NYC Department of Buildings' project records provide additional market and development context.
Professional underwriting also considers project-specific financial information, construction schedules and the developer's execution plan.
Capital structure matters as well. An EB-5 loan's position relative to other financing affects its contractual repayment priority, as explained in ARCFE's guide to understanding the EB-5 capital stack.
Together, these factors help investors assess whether the financing structure and repayment strategy fit the underlying development.
4. How Does Project Loan Repayment Relate to Investor Principal Repayment?
In a loan-based EB-5 structure, the project borrower generally repays the loan to the NCE.
The NCE then manages any distributions to eligible investors in accordance with the investment documents and applicable EB-5 requirements.

Project loan repayment and investor principal repayment are two distinct steps.
ARCFE explains this distinction in What EB-5 Capital Repayment Really Means.
Investors can also review our article on the EB-5 Sustainment Period to understand how immigration investment requirements interact with capital planning.
The iCross × ARCFE Perspective
ARCFE was founded by iCross Capital, a New York City real estate credit institution with nearly 20 years of lending experience.
That background shapes our approach to evaluating EB-5 real estate investments, with attention to project fundamentals, financing structure, local market demand and repayment planning.
At iCross × ARCFE, we believe a well-structured investment begins with a clear understanding of how a project's business plan supports its financing obligations. Ongoing project monitoring and disciplined capital management remain important throughout the investment lifecycle.
For EB-5 investors, understanding the proposed repayment strategy provides another perspective when evaluating both a project and the regional center behind it.
Disclaimer: This article is for general informational purposes only and does not constitute legal, immigration, tax, or investment advice. Loan repayment and investor distributions depend on project performance, governing documents and applicable EB-5 requirements. EB-5 investments involve risk, and repayment of principal is not guaranteed.
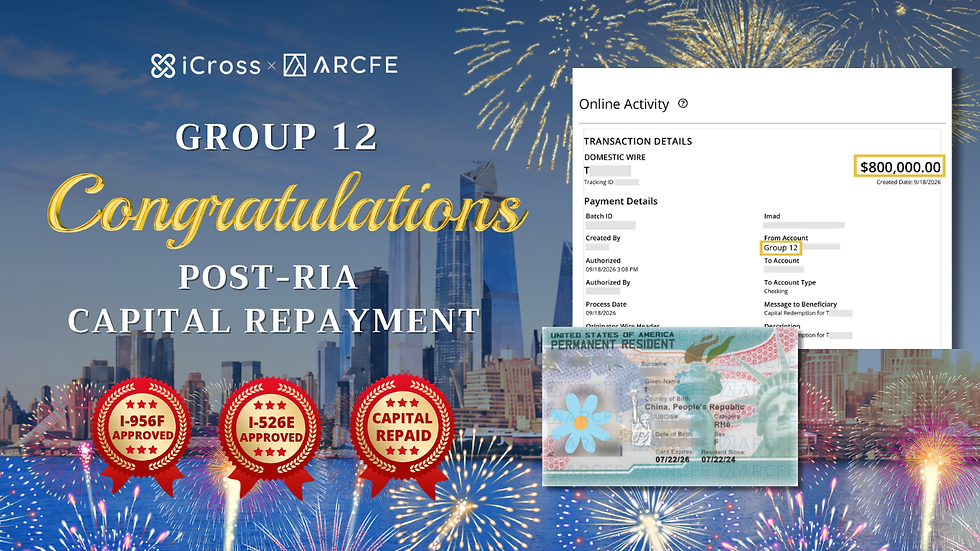
Recent ARCFE EB-5 Principal Repayment Highlights
Explore ARCFE’s latest EB-5 principal repayment milestones across pre-RIA and post-RIA projects. Click any image below to read the full project update.

Explore Current New York Real Estate-Backed EB-5 Opportunities


Considering EB-5 for Your Family?
Speak with an iCross × ARCFE EB-5 specialist to discuss your immigration goals, timeline, and available investment opportunities.
Related ARCFE Resources
Review important travel, residency, tax and immigration considerations after receiving a conditional green card.
Understand how senior debt, mezzanine financing and equity differ in repayment priority and risk exposure.
For more on this topic, read What EB-5 Capital Repayment Really Means.


