High-Unemployment Area vs. Rural EB-5 Projects: Why Urban Market Fundamentals Matter

Updated: 2 days ago

Short answer: High-Unemployment Area and Rural EB-5 projects can both qualify for the reduced $800,000 investment threshold and reserved visa categories. Their immigration treatment differs, but neither designation determines the financial quality of the underlying investment. USCIS currently confirms the $800,000 minimum for qualifying TEA investments. Review the USCIS investment requirements.
For investors considering an urban High-Unemployment Area project, the more important question is what sits behind the designation: the strength of the market, the developer, the financing structure, collateral, job creation and the project's path to repayment.
In established markets such as New York City, a qualifying High-Unemployment Area project can combine EB-5 immigration benefits with the advantages of investing in a large, transparent and highly active real estate market.

High-Unemployment Area and Rural EB-5 Projects: The Key Differences
Under the EB-5 Reform and Integrity Act, both High-Unemployment Areas and Rural Areas fall within the Targeted Employment Area, or TEA, framework.
High-Unemployment Area | Rural Area | |
Minimum qualifying investment | $800,000 | $800,000 |
Reserved EB-5 visas | 10% | 20% |
Rural-specific processing priority | No | Yes |
Determines investment quality? | No | No |
As of the September 2026 Visa Bulletin, both High-Unemployment and Rural reserved EB-5 categories remain Current for all chargeability areas. Visa availability can change, so investors should always review the latest Department of State Visa Bulletin.
The immigration differences matter. But they are only one part of the investment decision.
Why High-Unemployment Area Projects Can Still Be in Strong Urban Markets
The term “High-Unemployment Area” can be misleading to investors who are unfamiliar with EB-5.
It does not necessarily mean that a project is located in a weak, remote or declining real estate market.
Under EB-5 rules, a High-Unemployment Area is determined using the applicable geographic and unemployment methodology. The relevant area must meet an unemployment threshold of at least 150% of the national average. More information is available through the USCIS EB-5 Immigrant Investor Program.
That means qualifying High-Unemployment Area projects can exist within major metropolitan markets, including New York City.
This distinction matters because an urban project's investment fundamentals may be very different from what the words “high unemployment” initially suggest.
A well-located New York project may still benefit from:
established residential and commercial demand;
extensive transportation and public infrastructure;
a deep network of banks, institutional lenders and real estate investors;
substantial transaction, leasing and sales data for underwriting;
and a broader pool of potential buyers, tenants and refinancing sources.
These characteristics do not eliminate investment risk. They do, however, give investors and lenders more market evidence with which to evaluate a project's assumptions and potential exit strategy.
Current market conditions also matter. CBRE's 2026 New York City outlook describes strong demand for high-quality assets, constrained supply in parts of the market and continued activity across the city's capital markets. These are market-level indicators rather than guarantees for any individual project, but they illustrate why location and market depth remain important parts of real estate underwriting.

Speak with an iCross × ARCFE EB-5 specialist to discuss your immigration goals, timeline, and available investment opportunities.
What About Rural EB-5 Projects?
Rural projects receive 20% of annual EB-5 visas and statutory processing priority, compared with the 10% set-aside for High-Unemployment Area projects. These can be meaningful considerations when planning an immigration strategy.
But those benefits relate to immigration treatment.
A Rural designation does not tell an investor whether a particular project has sufficient equity, conservative leverage, strong collateral, reliable market demand or a realistic repayment strategy.
The same principle applies to High-Unemployment Area projects.
Geographic designation alone is not an investment-quality rating.
What Investors Should Evaluate Beyond the EB-5 Category
For real estate-backed EB-5 investments, investors should look beyond the TEA designation and examine the project itself.
Key questions include:
How experienced is the developer?
How much developer equity is invested?
Where does EB-5 capital sit in the capital stack?
How much debt is ahead of the EB-5 investment?
What collateral supports the financing?
Is the construction budget fully funded and realistic?
Does the project have sufficient job-creation cushion?
What supports buyer or tenant demand?
How is the project expected to repay the EB-5 investment?
Two projects may both qualify for the same EB-5 category and still have very different financial structures and risk profiles.
Why New York Urban High-Unemployment Projects Matter to ARCFE
ARCFE has long focused on New York real estate-backed EB-5 investments, including projects located in qualifying urban High-Unemployment Areas.
For ARCFE, the value of this approach goes beyond TEA eligibility.
New York gives our team a market we know directly and can evaluate through a real estate lending lens. Project selection therefore considers not only whether a location satisfies EB-5 requirements, but also the underlying real estate fundamentals: developer experience, borrower equity, capital structure, collateral, construction progress, local demand and potential repayment sources.
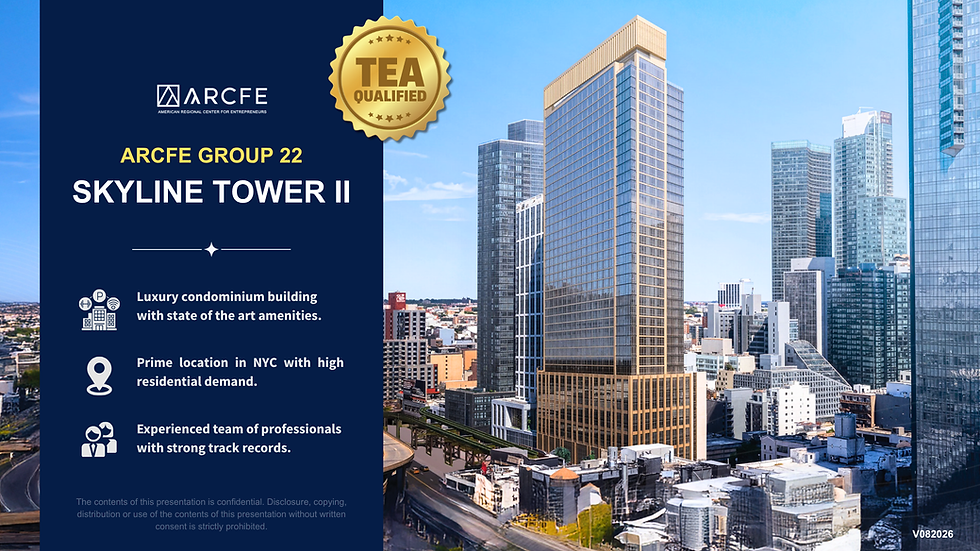
This is particularly relevant in markets such as Long Island City, Queens and other established New York neighborhoods, where an EB-5 project can qualify for High-Unemployment Area treatment while still being located within one of the country's deepest real estate markets. Investors can also review ARCFE Group 22 | Skyline Tower II for an example of ARCFE's New York urban project focus.
High-Unemployment Area eligibility is one layer of the analysis.
The investment case still has to stand on the strength of the project itself.
What Investors Should Take Away
For an EB-5 investor, the geographic category answers an important immigration question:
Which EB-5 category does the project qualify for?
The investment analysis requires a different set of questions:
Where is the project located? How is it financed? What supports demand? What protects the capital? And what is expected to support repayment?
For investors considering an urban High-Unemployment Area project, particularly in New York, the opportunity is to evaluate both sides of the equation: the available EB-5 immigration treatment and the fundamentals of an established urban real estate market.
A geographic designation can determine the EB-5 category.
Long-term investment quality still depends on underwriting.
For deeper project due diligence, see Beyond the Pitch Deck: How Serious EB-5 Investors Should Evaluate a Project, EB-5 Investing 101: Measuring Risk Through the Capital Stack, and Why Location & Market Demand Matter in an EB-5 Investment.
This article is for educational purposes only. Visa availability and USCIS policies may change. EB-5 investments involve risk, including the possible loss of principal. Investors should review the applicable offering documents and consult independent immigration, securities, tax and financial advisers before investing.
Recent ARCFE EB-5 Principal Repayment Highlights
Explore ARCFE’s latest EB-5 principal repayment milestones across pre-RIA and post-RIA projects. Click any image below to read the full project update.


Explore Current New York Real Estate-Backed EB-5 Opportunities

Considering EB-5 for Your Family?
Speak with an iCross × ARCFE EB-5 specialist to discuss your immigration goals, timeline, and available investment opportunities.
Related ARCFE Resources
Review important travel, residency, tax and immigration considerations after receiving a conditional green card.
Understand how senior debt, mezzanine financing and equity differ in repayment priority and risk exposure.